
By E-commerce 4 Internet Marketers Editorial
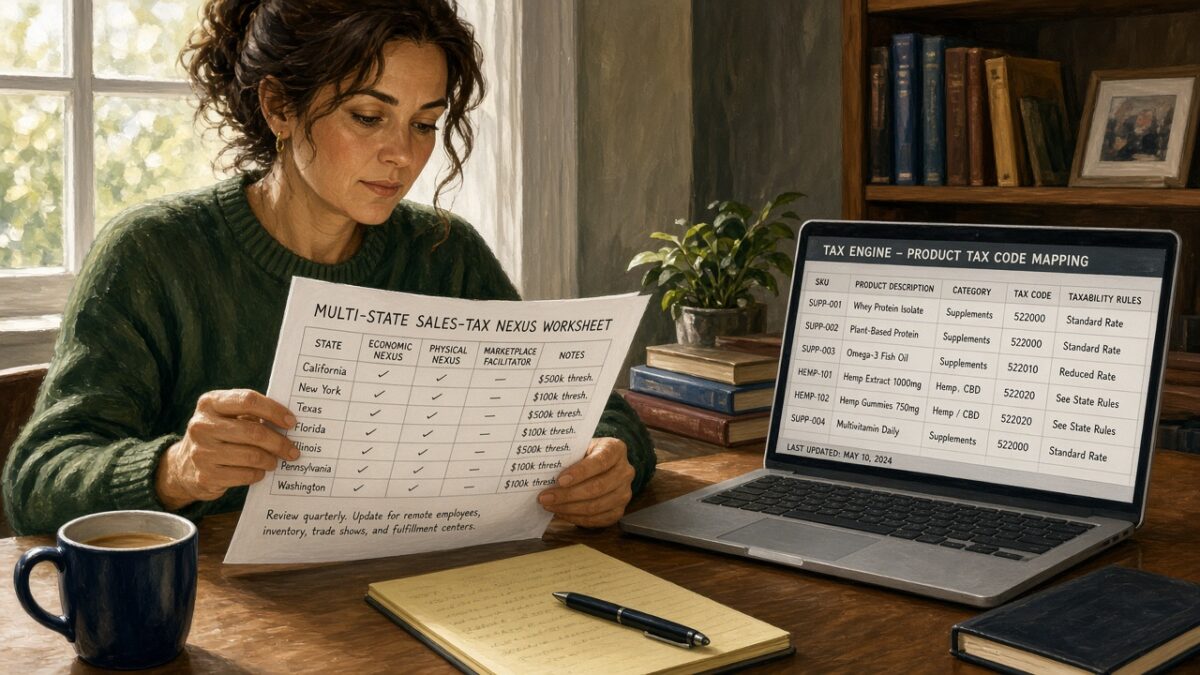
Explainer. Website owners and developers who ship supplements, hemp-derived goods, or other specialty catalogs across state lines face two separate sales-tax problems. First is nexus, meaning when a state can require collection and remittance. Second is product taxability, meaning whether a SKU is taxed like food, a dietary supplement, tangible personal property, or something else. Tax engines only help when both the nexus configuration and the product tax codes match how each jurisdiction actually classifies the goods. This article is high-level orientation for storefront and platform teams. It is not tax, legal, or filing advice. It does not invent current dollar thresholds for any state, and it does not declare whether a named SKU is taxable in a named state.
Why regulated catalogs feel nexus earlier than generic shops
Cross-state sellers of CBD, hemp derivatives, vitamins, herbals, topicals, and similar goods often hit compliance work before revenue looks “enterprise scale.” Reasons that show up in ops reviews include:
- Destination volume. Direct-to-consumer shipping into many states creates separate remote-seller analyses even without warehouses in those states.
- Mixed catalogs. One cart may hold a Supplement Facts SKU, a Nutrition Facts food SKU, a topical, and a hemp-derived ingestible. Default “everything taxable” settings produce wrong invoices and wrong exemption assumptions.
- Marketplace and direct channels. Marketplace facilitator collection on some channels does not automatically clean up tax settings on the brand’s own Shopify, WooCommerce, or headless checkout.
- Audit and withholding surprises. Wrong rates and wrong product classes create under-collection, over-collection, or unexpected marketplace withholding that finance teams discover after payout.
The Federation of Tax Administrators (FTA) maintains a public member map of state tax agencies and publishes policy resolutions that treat remote-seller collection authority as settled after South Dakota v. Wayfair. FTA Resolution 2024-2 summarizes that on June 21, 2018 the U.S. Supreme Court overruled the physical-presence rule of Quill for sales and use tax collection, and that states have since enacted remote-seller collection laws within constitutional limits. Use FTA’s member links to reach official department of revenue (DOR) pages, not secondary “threshold blogs,” when confirming registration rules.
Economic nexus after Wayfair (high level)
The Streamlined Sales Tax Governing Board’s Remote Sellers FAQ states that the Supreme Court ruled in South Dakota v. Wayfair on June 21, 2018 that states can require sellers to collect and remit sales or use tax on sales delivered into the state regardless of physical presence. The official slip opinion is South Dakota v. Wayfair, Inc., No. 17-494 (585 U.S. 162 (2018)).
What website teams should take from that framework without treating any blog chart as gospel:
- Physical presence is no longer the sole sales-tax collection gate. Economic activity into a state can create a collection duty when the state’s statute applies.
- Physical presence still matters. Streamlined’s FAQ states that Wayfair did not change registration obligations for sellers that already have physical presence in a state. Inventory, employees, offices, and similar contacts still need separate review with counsel and the state.
- States set their own remote-seller thresholds and measurement rules. Streamlined’s Remote Seller State Guidance page explains that many states use sales or transactions, some use sales and transactions, and a state may base the sales test on gross sales, gross revenues, retail sales, or taxable sales. That page also states its chart is general guidance, not legal advice, and that nothing in the chart overrides an individual state’s laws.
- Do not hard-code invented dollar amounts into cart software. Threshold dollars, lookback periods, and whether marketplace sales count toward a seller’s own threshold change by statute and guidance. Point engineering and finance at the Streamlined chart plus each state’s remote-seller page via FTA member sites, then store counsel-approved values in a versioned config, not in theme copy.
Streamlined also documents how the same sales figure can count differently depending on the state’s measurement base. Its Remote Seller Threshold Terms page walks through identical example sales that produce different threshold totals under gross sales, retail sales, and taxable sales definitions. For regulated catalogs, exempt or nontaxable lines (resale certificates, product exemptions such as food in some states) can still matter for gross or retail tests even when little tax is collected on those lines. That is a common source of “we thought we were under the threshold” surprises.
Streamlined’s disclosed-practice work has also published best-practice language that member states not maintain a transactional economic nexus threshold, and that registration/collection start no sooner than the first day of the first calendar month that begins 30 days after meeting or exceeding the state’s threshold (2023-01 Economic Nexus Threshold Best Practices). Best practices are not automatic law in every state. Confirm each destination against that state’s current guidance.
For orientation only, the Court in Wayfair reviewed South Dakota’s then-challenged statute, which used an economic nexus construct built around substantial in-state sales volume (commonly described in the opinion and later Streamlined materials by reference to South Dakota’s small-seller protections). That historical fact is not a license to paste one dollar figure into every state’s tax plugin.
Marketplace channels versus the brand storefront
Streamlined’s Remote Seller State Guidance notes marketplace facilitator programs in many states’ remote-seller materials. High-level implications for regulated brands:
- Facilitator collection on Amazon, Walmart, or similar channels is a marketplace compliance path, not a substitute for configuring tax on the merchant’s own site.
- Whether marketplace sales count toward a remote seller’s own economic nexus threshold is a state-specific question. Do not assume either inclusion or exclusion without the state’s guidance.
- Direct site, wholesale portals, and subscription carts remain the developer’s responsibility for rate, product class, exemption certificates, and filing integrations.
Product taxability nuances for supplements
Sales tax engines fail when every SKU inherits a default “tangible personal property” or “general merchandise” class. Dietary supplements are a named product class in Streamlined Sales and Use Tax Agreement (SSUTA) library definitions.
A published Streamlined Agreement appendix defines “dietary supplement” (in substance) as a product other than tobacco that is intended to supplement the diet, contains specified dietary ingredients (vitamin, mineral, herb or other botanical, amino acid, dietary substance to increase total dietary intake, or concentrate/metabolite/constituent/extract/combination), is intended for ingestion in tablet, capsule, powder, softgel, gelcap, or liquid form (or is not represented as conventional food or as a sole item of a meal or diet if not in those forms), and is required to be labeled as a dietary supplement identifiable by the “Supplemental Facts” box under 21 C.F.R. § 101.36 (SSUTA appendix wording). The same library defines “food and food ingredients” as substances sold for ingestion or chewing by humans for taste or nutritional value, excluding alcoholic beverages and tobacco, and states that a member state may exclude candy, dietary supplements, and soft drinks from the food definition (Streamlined Sales and Use Tax Agreement definitions appendix, New Mexico legislative reprint).
Practical storefront consequences:
- Label drives class. Supplement Facts versus Nutrition Facts is not cosmetic. Mis-tagging a Supplement Facts SKU as “food” in the tax engine can under-collect in jurisdictions that tax supplements while exempting many foods.
- Member states can treat supplements differently from food. SSUTA uniformity is about shared definitions states may adopt or exclude from. It is not a single national taxability answer for every vitamin SKU.
- Verified state example (not a 50-state map). Washington Department of Revenue’s Sales of dietary supplements page states that sales of dietary supplements are subject to retail sales tax, restates the three-part definition aligned with the federal Supplement Facts requirement, and states that products labeled with both Supplement Facts and Nutrition Facts boxes are not dietary supplements and are treated as food and food ingredients (exempt from retail sales tax unless taxable as soft drink or prepared food). That is Washington’s published rule. Do not extrapolate it to other states without their primary guidance.
Hemp and CBD taxability is not Farm Bill legality
Federal hemp descheduling and FDA product-type rules answer different questions than state sales tax. A SKU may be “Farm Bill hemp” for controlled-substance analysis and still be taxed (or restricted) under state sales and use tax rules that look at how the product is sold and labeled. This article does not invent whether CBD oil, gummies, topicals, or delta-8 products are taxable in any named state.
What developers can verify without inventing taxability:
- Tax engines publish product categories for industrial-hemp CBD and for supplements so jurisdiction rules can attach to the right class. Avalara’s public Tax Codes Search lists goods and services types that include “CBD products from industrial hemp” and dietary-supplement trees (for example Supplement Facts-labeled vitamins and related supplement codes). Avalara’s search UI also states that the merchant remains responsible for choosing appropriate codes.
- Collapsing every hemp SKU into one “CBD” or one “supplement” code is a common failure mode. Topicals, ingestibles, pet products, and cosmetics can follow different taxability paths even when marketing copy uses one brand story.
- Counsel and tax advisors should map each product class to primary state guidance before engineering locks a default.
Why tax engines need accurate product tax codes
Rate lookup by ZIP alone cannot encode food-versus-supplement distinctions, clothing exceptions, or hemp-specific classes. Verified product-code mechanisms:
TaxJar. TaxJar’s API docs state that product-level tax rules use product_tax_code on line items, that fully taxable goods need no code, and that categories cover goods that are exempt or reduced in some jurisdictions. The published category list includes Supplements with code 40020 (“Non-food dietary supplements”) and Food & Groceries with code 40030 (“Food for human consumption, unprepared”), among others (TaxJar Categories API; Sales Tax Calculations guide). TaxJar also documents that calculation requests should reflect merchant nexus addresses, and that without nexus in the destination state the API path for collection differs. Passing 40030 on a Supplement Facts SKU is a configuration error, not an engine bug.
Shopify Tax. Shopify Help states that for U.S. merchants, product categories indicate tax obligations and exemptions, that categories come from Shopify’s Standard Product Taxonomy, and that correct categorization supports more accurate tax collection. Shopify also warns that collecting too much or too little sales tax can create financial or legal liability, and that category-based U.S. tax calculation may be in early access for some stores (Manage your US taxes; Shopify's Standard Product Taxonomy). Overrides remain available when default category rules do not fit, with Shopify’s caution that state-level overrides may not collect local taxes.
Avalara AvaTax. Avalara publishes a browsable tax-code directory for mapping items to goods and services types, including CBD-from-industrial-hemp and dietary-supplement codes (Tax Codes Search). Avalara’s search page states merchants remain responsible for choosing appropriate codes. Prefer Avalara-published codes that match the SKU’s label and form factor before inventing free-text classes. Where a catalog needs a code the public directory does not cover, treat that as a counsel-and-vendor configuration task (Avalara documents custom tax-code workflows in its knowledge center) rather than leaving the SKU on a generic taxable default.
Shared engineering pattern for high-risk catalogs:
- Maintain a product tax class table (SKU or variant → tax engine code → label type → counsel cite).
- Sync that table into TaxJar
product_tax_code, Avalara item tax codes, and Shopify product categories (or the connector’s equivalent). - Regression-test carts that mix food, supplement, topical, and hemp lines into several destination states where the brand has nexus.
- Re-review mappings when labels change (for example Nutrition Facts added beside Supplement Facts) because tax class can change with the label under rules like Washington’s.
Operations checklist for website owners and developers
- Separate nexus config from product taxability config. One answers “must we collect in this state?” The other answers “what rate and base apply to this SKU?”
- Pull thresholds only from Streamlined Remote Seller State Guidance and state DOR pages linked from FTA. Version the values. Do not scrape unofficial charts into production.
- Measure sales the way the destination state measures them (gross, retail, or taxable). Streamlined’s threshold-terms examples show why the distinction matters.
- Classify SKUs by label and form, not by marketing category alone. Align Supplement Facts goods to supplement codes such as TaxJar
40020when that is the correct class, not to food codes. - Give hemp and CBD their own classes in the tax engine where the vendor provides them (for example Avalara’s industrial-hemp CBD goods types). Do not invent state taxability in code comments.
- Do not treat marketplace facilitator collection as a full substitute for brand-site tax configuration.
- Keep exemption certificates and resale flows out of the same default path as retail DTC SKUs.
- Log tax engine request IDs, product codes, and nexus flags on the order for audit support.
- Schedule counsel review when Streamlined or state remote-seller guidance changes, not when a blog posts a new “2026 nexus chart.”
What this article deliberately omits
- Any invented current dollar nexus threshold presented as law for a named state.
- A 50-state taxability matrix for vitamins, CBD, delta-8, topicals, or pet hemp products.
- Filing calendars, penalty estimates, or registration how-tos presented as advice.
- Claims that a tax engine “guarantees” compliance for regulated catalogs.
- Income-tax, franchise-tax, or business-activity-tax nexus analysis (FTA materials discuss those separately from sales-tax remote sellers).
Those omissions keep the article usable for developers who need architecture and sourcing discipline without fake certainty.
Sources
- Federation of Tax Administrators, Home / member agency map.
- Federation of Tax Administrators, Resolutions (including Resolution 2024-2, Remote Seller Collection Authority, discussing Wayfair).
- U.S. Supreme Court, South Dakota v. Wayfair, Inc., No. 17-494 (June 21, 2018).
- Streamlined Sales Tax Governing Board, Remote Sellers FAQ.
- Streamlined Sales Tax Governing Board, Remote Seller State Guidance.
- Streamlined Sales Tax Governing Board, Remote Seller Threshold Terms.
- Streamlined Sales Tax Governing Board, 2023-01 Economic Nexus Threshold Best Practices.
- Streamlined Sales and Use Tax Agreement definitions appendix (dietary supplement and food definitions), New Mexico legislative reprint PDF.
- Washington Department of Revenue, Sales of dietary supplements.
- Avalara, Tax Codes Search (includes CBD products from industrial hemp and dietary supplement goods types).
- TaxJar Developers, List tax categories / API Reference (includes Supplements
40020). - TaxJar Developers, Sales Tax Calculations.
- Shopify Help, Manage your US taxes.
- Shopify Help, Shopify's Standard Product Taxonomy.